Table of Contents
- Top 5 Types of Personal Injury Claims UK: Quick Comparison
- 1. Road Traffic Accident Claims
- 2. Accident at Work Claim Process
- 3. Slips, Trips and Falls in Public Places
- 4. Medical Negligence Claims
- 5. Industrial Disease and Long-Term Illness Claims
- Personal Injury Claim Time Limit UK: What You Need to Know
- How No Win No Fee Personal Injury Claims Work
- Frequently Asked Questions
Last Updated: September 13, 2026
Top 5 Types of Personal Injury Claims UK: Quick Comparison
Most people only discover how personal injury claims work after an accident has already happened, which is exactly when clear information matters most. This guide from Claims 24 breaks down the top 5 types of personal injury claims UK claimants pursue each year, from road traffic accidents to industrial disease, so you know where your situation fits and what comes next.
A personal injury claim is a legal request for compensation after an injury caused by someone else’s negligence. The type of claim depends on where and how the injury happened, and each route carries its own evidence requirements and typical timescales.
| Claim Type | Typical Scenario | Who You Claim Against |
|---|---|---|
| Road traffic accident | Driver, passenger, cyclist or pedestrian injured by a vehicle | The at-fault driver’s insurer |
| Accident at work | Injury caused by unsafe conditions or employer negligence | The employer’s liability insurer |
| Slip, trip or fall in public | Fall in a shop, on a pavement or in a leisure venue | The occupier’s insurer |
| Medical negligence | Harm caused by a GP, hospital or clinician | The NHS trust or private provider |
| Industrial disease | Long-term illness from workplace exposure | Former employer’s insurer |
The five claim types below cover the vast majority of cases, and the process for each follows a similar shape: establish fault, gather evidence, and negotiate or litigate for compensation.
1. Road Traffic Accident Claims
Road traffic accident claims are the most common personal injury claims, covering drivers, passengers, motorcyclists, cyclists and pedestrians injured by another road user. You claim against the at-fault driver’s insurer, not the driver personally.
Common scenarios include rear-end shunts at roundabouts, motorway pile-ups, a motorcyclist struck at a junction, and pedestrians hit on a crossing. Whiplash remains the most frequent injury, though fractures and head injuries are also widespread.
Evidence wins these cases. Photographs of vehicle damage, dashcam footage, witness details and the police incident reference number all strengthen your position. Report the accident to your insurer promptly even when you are not at fault, because most policies require notification.
Insurers often make a quick settlement offer within days of a collision. Accepting it usually closes the claim permanently, even if your symptoms worsen later. Have the offer reviewed before you sign anything.
2. Accident at Work Claim Process
The accident at work claim process begins with reporting the injury to your employer and recording it in the accident book. From there, the claim rests on showing that your employer failed in a duty of care owed to you under the Health and Safety at Work etc. Act 1974, which you can review via the official legislation record for the Health and Safety at Work etc. Act 1974.
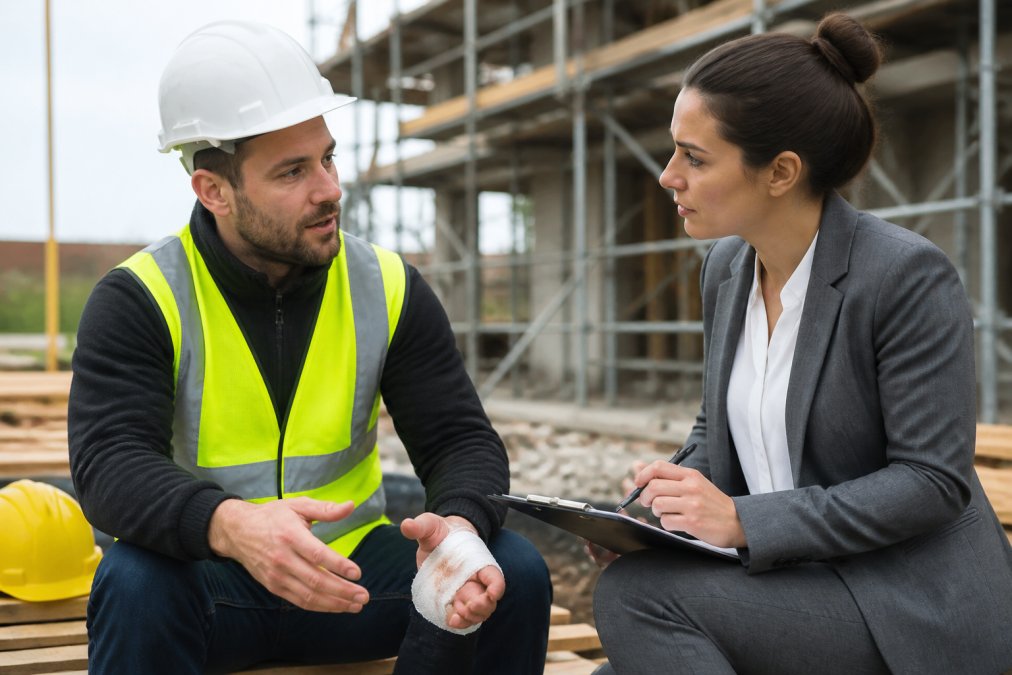
Typical workplace claims involve falls from height, moving machinery, lifting injuries, and slips on wet floors. The key question is rarely whether the accident happened, but whether the employer did enough to prevent it.
Your employer must hold employers’ liability insurance, so compensation is paid by their insurer rather than the business directly. Employers cannot lawfully dismiss you for bringing a claim. Keep payslips, medical records and any correspondence about the incident, because loss of earnings forms part of the compensation.
3. Slips, Trips and Falls in Public Places
Slips, trips and falls in public places fall under occupiers’ liability, meaning the person or organisation controlling the space owes visitors a duty of care. Supermarkets, councils, pubs and shopping centres are the usual defendants.
These claims are harder than they look. You must show a hazard existed and that the occupier failed to deal with it. A wet floor with no warning sign, a broken paving slab reported weeks earlier, or a spillage left unattended all support a claim. The date, time and exact location matter enormously, so note them immediately.
Occupiers frequently deny that a hazard existed or claim they inspected regularly. Without photographs, witness details or an incident report reference, these claims become difficult to prove.
4. Medical Negligence Claims
Medical negligence claims arise when a GP, hospital or clinician provides care below the standard reasonably expected, and that failing causes harm. These are among the most complex personal injury claims because two things must be proven: that the care was negligent, and that the negligence directly caused the injury.
Misdiagnosis, delayed diagnosis, surgical errors and medication mistakes are common grounds. A GP who fails to refer a patient with clear warning signs, or a hospital that leaves a condition untreated, may both be negligent.
Clinical negligence cases take longer than most other claim types, often because expert medical evidence is required on both sides. Many firms handle these on a no win no fee basis so there is no upfront cost to you.
5. Industrial Disease and Long-Term Illness Claims
Industrial disease claims cover illnesses that develop after years of workplace exposure, such as asbestos-related conditions, hearing loss from noisy environments, and respiratory disease from dust or fumes. Symptoms often appear decades after the exposure, which makes these claims distinct from accident claims.
The employer’s breach of duty usually happened years ago, so tracing employment history, payslips and medical records becomes central to the case. Time limits can be more flexible here because the clock generally starts from the date you knew, or should reasonably have known, that your condition was linked to work.
These cases demand specialist legal advice. Evidence gathering takes time, and insurers contest causation vigorously.
Personal Injury Claim Time Limit UK: What You Need to Know
The personal injury claim time limit UK claimants face is generally three years from the date of the accident, or from the date you knew you had suffered an injury. This is set out in the Limitation Act 1980, which you can check through the official record of the Limitation Act 1980.
Different rules apply to children, who generally have three years from their eighteenth birthday, and to claimants without mental capacity. Industrial disease cases run from the date of knowledge rather than exposure.
Missing the deadline usually bars your claim entirely, so seek advice as soon as you suspect negligence. The official guidance on claiming compensation for a personal injury confirms how these limits operate in practice, and a solicitor can confirm exactly when your clock started.
How No Win No Fee Personal Injury Claims Work
No win no fee personal injury claims operate under a conditional fee agreement, meaning you pay nothing if the claim fails. If it succeeds, your solicitor’s fee is recovered from the opponent’s insurer, with any shortfall covered by a success fee that is capped by law.
The arrangement removes the financial risk of pursuing compensation, which matters when an injury has already reduced your income. You should still read the agreement carefully to understand what you might owe if the case succeeds.
At Claims 24, every claim is handled on a no win no fee basis, with in-house solicitors providing legal advice at each stage. The team offers a free consultation, support seven days a week, and a service tailored to your circumstances, whether that means face-to-face meetings or handling everything by phone and email. Claims 24 also pursues the maximum compensation for injury, loss of earnings, treatment and rehabilitation costs.
Frequently Asked Questions
What is the personal injury claim time limit UK?
For most personal injury claims, the time limit is three years from the date of the accident or from when you first became aware of the injury. There are exceptions for children, who have three years from their 18th birthday, and for industrial disease cases where the clock starts from the date of knowledge. Missing the deadline usually means losing the right to claim, so it is worth taking legal advice early.
How is compensation calculated for personal injury claims?
Compensation has two parts: general damages for the pain, suffering and loss of amenity caused by the injury, and special damages for financial losses such as lost earnings, medical treatment, rehabilitation costs and damaged property. General damages are assessed using guidelines that set ranges for different injury types and severities. The evidence you provide, including medical reports and payslips, directly affects the final figure.
Do I need a solicitor to make a personal injury claim?
You can pursue a claim yourself, but personal injury law involves strict procedural rules, deadlines and evidence requirements. A solicitor handles the paperwork, gathers medical evidence, negotiates with the other side’s insurers and represents you if the case goes to court. Many firms offer no win no fee personal injury claims, which means you pay nothing upfront and nothing if the claim is unsuccessful.
Can I claim for an accident at work if I am self-employed?
Self-employed workers can claim if someone else’s negligence caused the injury. For example, if you are a self-employed contractor and a site manager fails to cordon off a hazard, you may have a claim against that party. The accident at work claim process is similar to that for employees, but establishing who owed you a duty of care is the key step. Speak to a solicitor to assess whether liability can be proven.
What evidence is required for a personal injury claim?
Strong evidence includes medical records and reports, photographs of the accident scene and your injuries, witness statements, accident book entries, CCTV footage and receipts for expenses. Keep a diary recording how the injury affects your daily life, including pain levels and missed activities. The more documented evidence you have, the easier it is to prove both liability and the extent of your losses.
Knowing which category your injury falls into is the first step toward the compensation you are owed, and the second is acting before the three-year clock runs out. Claims 24 combines no win no fee funding, in-house solicitors and 24/7 support to guide claimants through road traffic accidents, workplace injuries, public place falls, medical negligence and industrial disease. Get started with Claims 24 and pursue the maximum compensation for your injury with a free consultation today.