Table of Contents
- What to Do Immediately After a Non-Fault Accident
- How to Claim for a Non-Fault Accident: A Step-by-Step Guide
- Evidence Needed for a Road Traffic Accident Claim
- Personal Injury Claim Time Limits in the UK
- Common Mistakes to Avoid After a Non-Fault Accident
- How Claims 24 Can Help You Claim Compensation
- Frequently Asked Questions
Last Updated: September 21, 2026
What to Do Immediately After a Non-Fault Accident
Knowing the steps to take after a non-fault accident protects both your health and your right to compensation. The moments right after a crash matter more than most drivers realise.
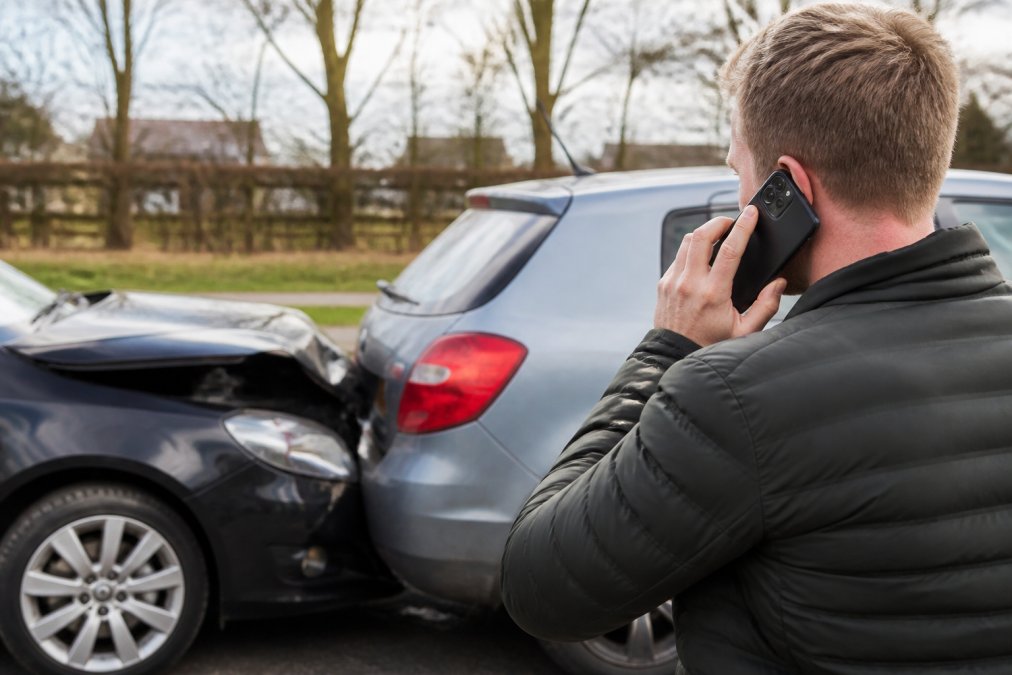
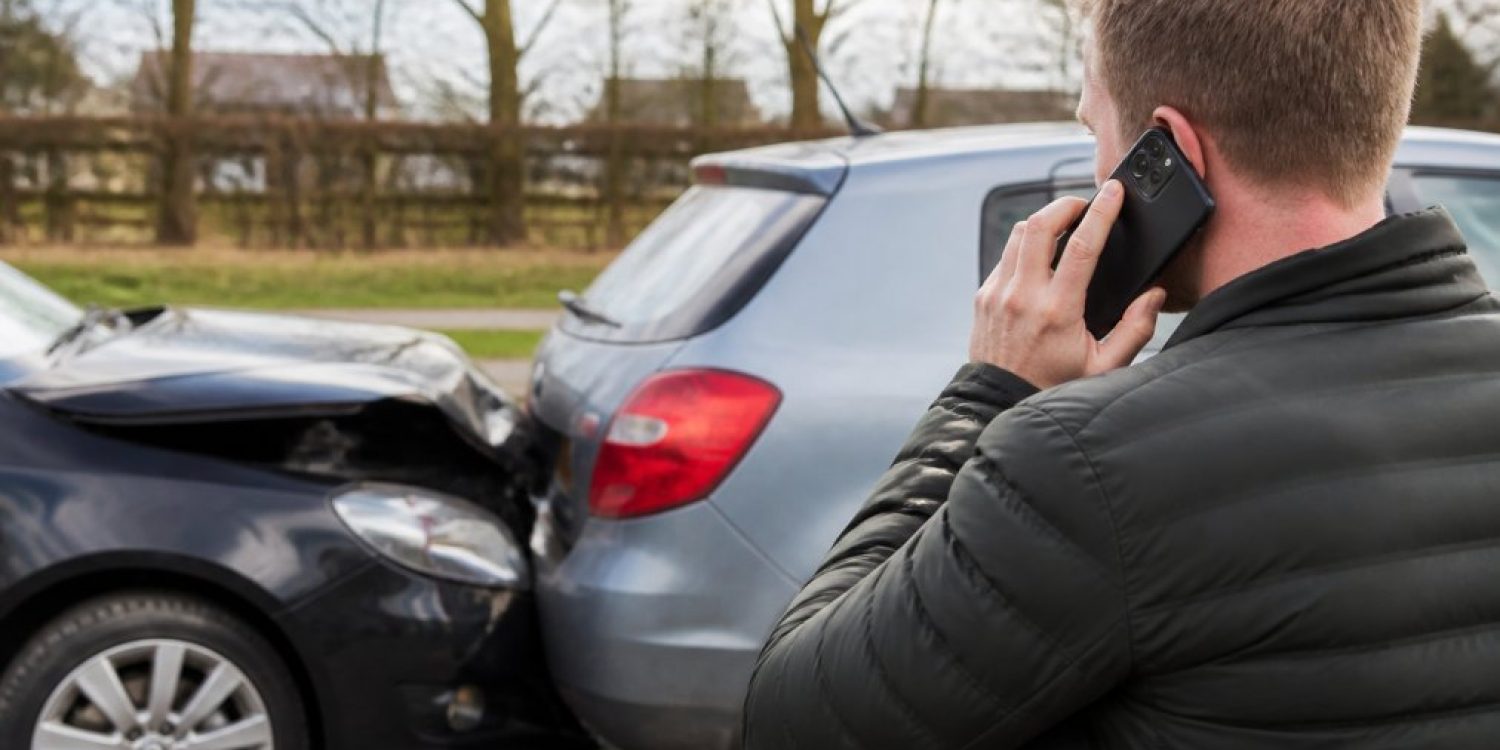
If another driver hits you, your first job is safety. Move to a safe spot if you can, switch on your hazards, and call 999 if anyone is hurt. Then swap details with the other driver and note their insurer.
This guide from Claims 24 walks you through each step.
Here is what to do at the scene:
- Stop and stay calm. Never drive off, even if damage looks minor.
- Check for injuries. Call 999 for an ambulance if needed.
- Move to safety. Pull over if the cars are blocking traffic.
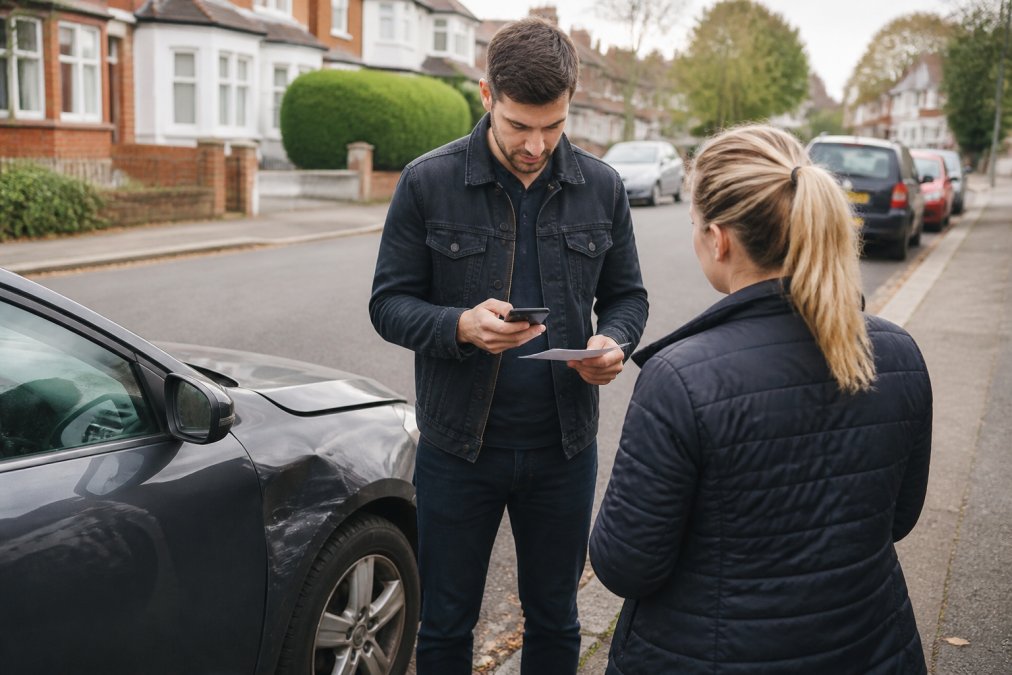
- Swap details. Names, addresses, phone numbers, and insurance details.
- Note the other driver’s registration and car make.
- Photograph everything. Damage, positions, road layout, and any injuries.
- Collect witness details. Names and phone numbers.
- Report it to the police if someone is injured or the driver leaves.
A common mistake is admitting fault at the scene. Say nothing about blame, even if you feel fine. Fault gets decided later, using evidence.
How to Claim for a Non-Fault Accident: A Step-by-Step Guide
A non-fault accident claim starts with your insurer and often runs through a specialist solicitor. The exact route depends on whether the other driver admits fault.
Here is the process, step by step:
- Report the accident to your insurer. Do this within days, even if you are not claiming from them.
- Gather your evidence. Photos, witness details, and any dashcam footage.
- Get medical attention. See a GP or A&E and keep every record.
- Speak to a solicitor. A free consultation lets you check if you have a claim.
- Send a letter of claim. Your solicitor does this. It sets out what happened.
- The insurer investigates. They may admit fault, dispute it, or stay silent.
- Medical assessment. An expert reports on your injuries and recovery.
- Negotiate a settlement. Your solicitor pushes for the full amount you are owed.
- Settle or go to court. Most claims settle. A few go further.
If the other side disputes liability, a solicitor can still help. Many cases turn on evidence, not on who shouts loudest.
The official guidance on making a claim after a road accident explains the basics, but a solicitor handles the detail for you.
Evidence Needed for a Road Traffic Accident Claim
Strong evidence decides most road traffic accident claims. The more you collect early, the harder it is for an insurer to argue.
Gather these items where you can:
- Photos of vehicle damage from several angles
- Photos of the scene, including road markings and traffic signals
- Dashcam or CCTV footage
- Names and contact details of witnesses
- The other driver’s insurance and registration details
- A police reference number, if officers attended
- Medical records and receipts for treatment
- Proof of lost earnings if you took time off work
Keep a written diary too. Note your pain levels, missed work, and any help you needed at home. Insurers value this kind of record.
What most guides miss is how quickly footage disappears. CCTV often wipes after a short period, so request it fast.
If a business or council camera may have caught the crash, ask for the footage in writing the same week. Once it is overwritten, it is gone for good.
Personal Injury Claim Time Limits in the UK
Personal injury claim time limits in the UK are strict, and missing the deadline usually ends your chance to claim. For most injury claims, you have three years from the date of the accident to start court proceedings.
There are exceptions. For children, the three-year clock starts on their 18th birthday. For people who lack mental capacity, different rules apply.
The Limitation Act 1980 sets out these time limits. Because the rules can shift with your circumstances, check your own position early.
Do not wait for your injuries to heal before seeking advice. Evidence fades, memories blur, and insurers move on.
| Situation | When the clock starts | Typical limit |
|---|---|---|
| Adult injury claim | Date of the accident | 3 years |
| Claim for a child | Child’s 18th birthday | 3 years |
| Fatal accident claim | Date of death | 3 years |
| Mental capacity cases | Rules vary | Seek advice |
Common Mistakes to Avoid After a Non-Fault Accident
The biggest mistake is staying silent and hoping the insurer plays fair. Most people who lose out do so because of small errors early on.
Watch for these traps:
- Admitting fault. Even a casual apology can be used against you.
- Settling too fast. A quick offer often ignores future treatment costs.
- Skipping medical care. No records means no proof of injury.
- Posting on social media. Insurers check. A holiday photo can sink a claim.
- Missing the deadline. Three years feels long until it is gone.
- Dealing with the other insurer alone. They protect their own interests, not yours.
A common mistake is accepting the first offer. It rarely covers rehabilitation or lost earnings.
Never accept a settlement before your injuries have stabilised. Once you sign, you cannot reopen the claim, even if you need further treatment later.
How Claims 24 Can Help You Claim Compensation
Claims 24 makes the claims process simple, fair, and offers justice to all our clients. We handle personal injury claims on a no win no fee basis, so there is no upfront cost to you.
Our in-house solicitors give accurate legal advice at every stage. We work nationwide for clients in England and Wales, and we support you 7 days a week.
Here is what you get:
- A free consultation to check if you have a claim
- No win no fee, so no financial risk to start
- Help with road traffic accidents, workplace injuries, and medical negligence
- Support to claim for injury, lost earnings, and treatment costs
- Face-to-face or remote service, whichever suits you
We aim to settle most claims swiftly. Serious or complex cases can take longer, and we tell you that upfront.
The Motor Insurers’ Bureau can help when the other driver is uninsured or untraced, and we guide you through that route too.
Frequently Asked Questions
What information must I exchange after a non-fault road traffic accident?
You should exchange your name, address, phone number, insurance details, and vehicle registration with the other driver. If anyone is injured, call 999. It’s also wise to note the time, date, and location of the accident, and take photos of the scene and any damage. This information is crucial for your personal injury claim and will help your solicitor establish liability quickly.
How long do I have to make a personal injury claim in the UK?
In the UK, the standard time limit for making a personal injury claim is three years from the date of the accident. However, there are exceptions, such as for minors or those lacking mental capacity. It’s important to seek legal advice as soon as possible to ensure you don’t miss the deadline. Claims 24 offers a free consultation to discuss your case and the applicable time limits.
Do I need to report a non-fault accident to the police?
You must report an accident to the police if someone is injured, if there is damage to property or street furniture, or if the other driver fails to stop or provide their details. For minor accidents where no one is hurt and details are exchanged, reporting is not always required. However, informing the police can provide an official record that may support your claim. Always prioritise safety and call 999 if there are injuries.
How does a non-fault accident affect my no-claims bonus?
If the accident is not your fault, your no-claims bonus should generally be protected. However, you must inform your insurer about the accident, even if you’re not claiming on your own policy. Your insurer will then seek recovery from the at-fault driver’s insurer. It’s important to provide all evidence to support your non-fault status. Claims 24 can guide you through the process to help safeguard your no-claims bonus.
A non-fault accident can leave you injured, out of pocket, and unsure where to turn. The right support makes the difference between a fair outcome and a missed opportunity. Claims 24 offers no win no fee representation, in-house solicitors, and 24/7 support to help you claim the maximum compensation you deserve. Get started with Claims 24 and let our team handle the paperwork while you focus on recovery.